The conversation about taxes in Arizona often begins at a Scottsdale coffee shop or Tucson neighborhood gathering, where recent arrivals compare notes with longtime residents about their first tax seasons. The California transplant expresses pleasant surprise at Arizona’s flat 2.5% income tax, while the Illinois refugee celebrates escaping crushing property tax burdens. Yet the New Hampshire native discovers sales taxes they never faced before, and everyone puzzles through the intricacies of transaction privilege tax. This diverse chorus of tax experiences reflects Arizona’s unique fiscal structure—a system that rewards some situations while surprising others, demanding understanding rather than assumptions.
Taxes shape more than budgets in Arizona; they influence where people choose to live, how businesses operate, and which communities thrive. The state that attracts retirees with tax-friendly policies also needs revenue for schools and infrastructure serving growing populations. Understanding Arizona’s tax landscape means grasping not just rates and rules but the philosophy behind them—a Western approach favoring consumption taxes over income taxes, local control over centralized authority, and competitive positioning against neighboring states. For those considering Arizona home, tax implications deserve careful consideration alongside climate and lifestyle factors.
| Category | Details |
|---|---|
| State Income Tax | Arizona uses a flat income tax rate: 2.5% for all taxpayers (since tax year 2023). This makes it one of the lowest state income tax rates in the U.S. |
| Sales Tax (Transaction Privilege Tax) | State base rate: 5.6%. County and city taxes are added on top, so combined rates vary by location: for example 6.3% in unincorporated Maricopa County, 8.0% in Scottsdale, 9.1% in Phoenix and 10.2% in Florence. |
| Property Tax | Relatively low compared to the national average. |
| Vehicle Taxes | Vehicle License Tax (VLT) is based on 60% of the manufacturer’s base retail price, reduced 16.25% for each year after the first. |
| Corporate Income Tax | Flat 4.9% rate since tax year 2017 (it was 6.968% through 2013). |
| Capital Gains Tax | Taxed at the 2.5% flat rate, but 25% of net long-term capital gains on assets acquired after 2011 can be subtracted. |
| Property Tax Exemptions | • Senior valuation freeze (eligibility-based) • Disabled veteran exemptions • Limited primary residence exemptions via county programs |
| Tax Credits & Incentives | • Solar energy credit (state) • Public school & private school tuition tax credits • Charitable organization contribution credits • Business incentives: Qualified Facility credits for new or expanded facilities, R&D credits |
| Retirement Income Tax | • Social Security benefits: NOT taxed • Military pension: Fully exempt • Other pension/IRA/401(k): State tax applies at 2.5% (up to $2,500 of federal, state and local government pensions is exempt) |
| Estate or Inheritance Tax | Arizona has no estate tax and no inheritance tax. |
| Gas Taxes | • Gas tax: 19¢/gallon (among the lowest in the U.S.) |
| Rental & Commercial Tax Notes | Short-term rentals subject to combined TPT (similar to sales tax). Some cities require additional licenses and tourism taxes (Scottsdale, Sedona). |
Arizona’s income tax structure occupies middle ground among Western states—neither the zero-income-tax haven of Nevada nor the steep progressivity of California. The state uses a single flat income tax rate of 2.5%, in effect since tax year 2023, which replaced the previous graduated brackets. This flattening means a household earning $50,000 pays the same rate as one earning $500,000, reflecting Arizona’s philosophical preference for broad-based, low-rate taxation.
The practical impact varies significantly by taxpayer situation. Arizona taxes interest and dividend income the same as wages, though it lets taxpayers subtract 25% of net long-term capital gains on assets acquired after 2011. The retiree receiving pension income finds Arizona’s treatment relatively generous, with significant exemptions for Social Security and military retirement pay.
Standard deductions in Arizona align with federal amounts, simplifying calculation. The state offers fewer itemized deductions than some states, though charitable contributions and mortgage interest remain deductible.
Tax credits provide targeted relief for specific situations. The dependent tax credit offers $125 for each dependent under 17, modest but helpful. The credit for increased transaction privilege or excise taxes helps offset sales tax burden for lower-income households. The charitable contribution credit—allowing a dollar-for-dollar credit, up to an annual limit, for donations to qualifying Arizona charities—encourages local giving while reducing tax burden. These credits require active claiming rather than automatic application, rewarding taxpayers who understand the system.
Withholding and estimated payments follow familiar patterns for those experienced with state income taxes. Employers withhold based on submitted A-4 forms, with most taxpayers achieving reasonable accuracy. Self-employed individuals, retirees with investment income, and others with non-wage income navigate quarterly estimated payments. The April 15 deadline aligns with federal filing, and taxpayers who request an extension have until mid-October to file. Most Arizona returns are filed electronically, and refunds on e-filed returns are processed much faster than refunds on paper returns.
Arizona’s sales tax system, technically called Transaction Privilege Tax (TPT), confuses newcomers with both its name and structure. Unlike traditional sales taxes paid by consumers, TPT technically falls on businesses for the privilege of conducting business in Arizona. Businesses pass this tax on to consumers, making the practical effect identical to sales tax, but the legal distinction matters for compliance and collection. The state rate of 5.6% forms just the foundation, with counties and cities adding their own rates.
Combined rates vary widely, from 5.6% in unincorporated Mohave County to 11.1% in South Tucson, creating surprising variation within small geographic areas. Crossing from Phoenix (9.1%) into Scottsdale (8.0%) changes the rate by about one percentage point. This patchwork results from Arizona’s cities and towns independently setting their own TPT rates. Online shopping adds complexity—rates apply based on delivery address, meaning neighbors might pay different rates depending on municipal boundaries invisible on the ground.
What’s taxable proves equally complex. Restaurant meals face full TPT, while groceries are exempt from the state portion, though many cities still tax food for home consumption. Prescription medications escape taxation while over-the-counter drugs get taxed. Services generally avoid TPT, though specific categories like hotel stays, commercial rentals, and telecommunications face taxation. The inconsistency creates regular surprises—personal property rentals are taxed but residential rentals are not, digital goods taxation depends on delivery method.
For businesses, TPT compliance becomes operational necessity. Unlike states where sellers simply collect state-imposed tax, Arizona businesses must obtain TPT licenses from the state and potentially each municipality where they operate. Construction contractors face particular complexity under the prime contracting classification of TPT. Restaurants navigate additional taxes on top of TPT. Even casual sellers discover obligations—regular garage sale operators or online marketplace sellers might trigger licensing requirements.
The economic impact of TPT extends beyond collection mechanics. Border communities compete with lower-tax neighbors—Yuma residents might shop in California despite that state’s income tax, while Flagstaff loses sales to online retailers. The regressive nature of consumption taxes hits lower-income households harder, consuming larger percentages of their budgets. Yet TPT provides stable revenue through economic cycles, funding essential services when income tax revenues fluctuate. The tourist and snowbird populations contribute substantially through TPT, helping fund infrastructure they use without paying property or income taxes.
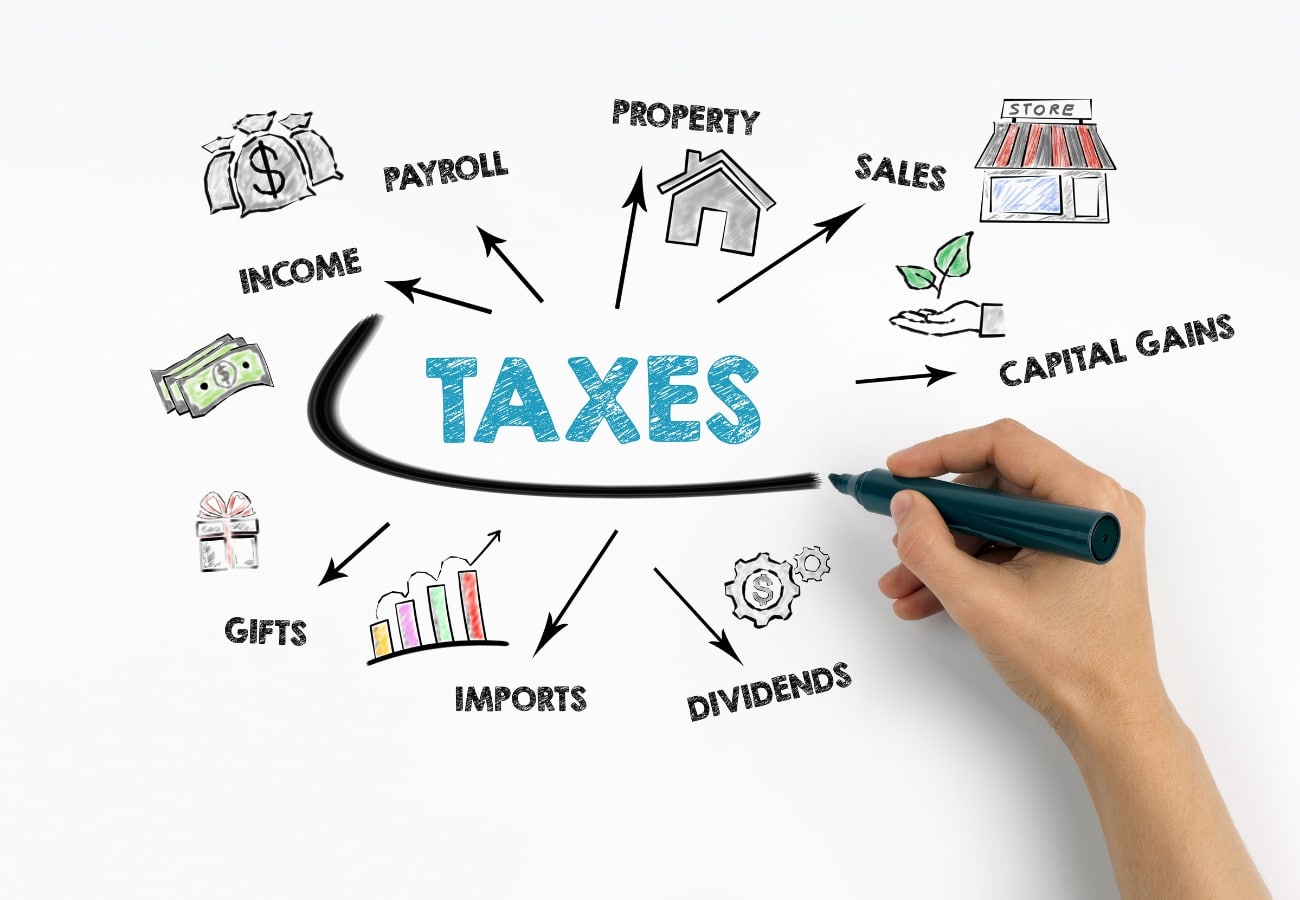
Property taxes in Arizona tell a story of restraint compared to many states, with effective rates below the national average. Yet this relatively low rate masks significant variation and complexity. Understanding property tax requires grasping assessment ratios, levy limits, and the powerful influence of voter-approved overrides.
Residential property assessment begins with “full cash value”—essentially market value determined by county assessors. Primary residences receive favorable treatment, assessed at 10% of their limited property value, which can be lower than full cash value. Second homes and residential rental properties are also assessed at 10%, while commercial properties are assessed at a higher ratio (stepping down to 15% from 2027), though special categories like agricultural land, golf courses, and historic properties receive preferential treatment.
The actual tax calculation multiplies assessed value by local tax rates, expressed in dollars per $100 of assessed value. The proliferation of special districts—fire, flood control, community college, hospital—each adds incremental rate increases.
Proposition 117, passed in 2012, limits assessed value increases to 5% annually regardless of market appreciation. This protection, similar to California’s Proposition 13 but less restrictive, prevents rapidly rising markets from forcing longtime owners from homes.
Property tax bills arrive in September with payment due in two installments—October and March. Most mortgage holders escrow taxes, never seeing bills directly. Those paying directly discover various payment options including online systems, though some jurisdictions still require physical checks. Seniors may qualify for property tax assistance programs, including deferrals allowing taxes to accumulate as liens paid upon sale. Low-income seniors might qualify for rebates, though amounts remain modest.
Tax appeals follow formal processes beginning with county assessors then potentially proceeding to state tax court. Success requires demonstrating over-valuation through comparable sales or assessment errors. The system favors status quo—assessors need not prove values correct, appellants must prove them wrong. Professional help often proves necessary for significant appeals, with property tax consultants working on contingency for commercial properties. Residential appeals typically involve owner representation, with mixed success depending on documentation quality and market conditions.
Arizona’s corporate income tax rate of 4.9% positions the state competitively among Western neighbors, though not at zero-tax Nevada’s level. This flat rate applies to all corporate income, avoiding the graduated structures complicating multi-state businesses elsewhere. Pass-through entities—LLCs, partnerships, S-corps—avoid entity-level taxation with income flowing to owners’ personal returns. This structure particularly benefits small businesses.
The corporate tax base includes standard adjustments familiar to multi-state businesses—apportionment formulas, net operating loss carryforwards, combined reporting requirements for unitary businesses. Arizona follows market-based sourcing for service revenue, beneficial for companies serving out-of-state customers. Manufacturing companies enjoy various deductions and credits, particularly for equipment purchases and research activities. The complexity requires professional tax assistance for all but simplest situations.
Business personal property tax adds another layer, taxing equipment, furniture, and fixtures used in business operations. Counties assess and collect these taxes locally, with rates and exemptions varying. Small businesses often qualify for exemptions on initial amounts of property value. Manufacturers receive favorable treatment for pollution control equipment and renewable energy systems. The administrative burden of listing and valuing business property annually frustrates small operators, though elimination proposals consistently fail given revenue impacts.
Transaction privilege tax obligations extend beyond simple retail sales for many businesses. Contractors navigate complex rules determining when they owe TPT versus when customers do. Professional service providers generally avoid TPT, though specific activities trigger obligations. Digital economy businesses face evolving requirements as Arizona adapts tax law to modern commerce. Multi-jurisdictional businesses might need dozens of licenses, each with distinct filing requirements and deadlines.
Tax incentives attempt to attract and retain businesses, though Arizona generally favors low overall rates over targeted incentives. Quality Jobs Tax Credit provides income tax relief for companies creating high-wage employment. Research and development credits reward innovation investment. Foreign trade zones reduce property tax burden for international commerce. Rural areas offer additional incentives addressing their competitive disadvantages. The Arizona Commerce Authority coordinates incentive programs, though negotiations occur case-by-case for major relocations.
Vehicle taxes surprise many Arizona newcomers with their complexity. The Vehicle License Tax (VLT) functions as personal property tax on vehicles, calculated on 60% of the manufacturer’s base retail price in the first year, with that value declining 16.25% each year after.
Estate planning in Arizona benefits from absence of state-level estate or inheritance taxes. Wealthy individuals flee states with such taxes for Arizona’s favorable treatment, though federal estate taxes still apply above exemption thresholds. The community property system affects estate planning, with specific rules for property acquired during marriage. Trusts remain popular for avoiding probate, managing incapacity, and controlling distributions. The intersection of tax planning and Arizona’s unique property laws requires specialized legal guidance.
Retirement taxation makes Arizona particularly attractive for retirees. Social Security benefits escape state taxation entirely. Military retirement pay receives generous exemptions. Private pension income faces standard income tax rates but at Arizona’s relatively low levels. Required minimum distributions from retirement accounts get taxed but without additional penalties some states impose. The combination of favorable tax treatment and climate draws hundreds of thousands of retirees, fundamentally shaping Arizona’s demographics and economy.
Sin taxes generate substantial revenue while theoretically discouraging consumption. Cigarette taxes at $2 per pack rank mid-range nationally. Alcohol taxes vary by type—beer, wine, spirits facing different rates. Marijuana taxation, following 2020 legalization, includes 16% excise tax plus standard TPT, generating hundreds of millions in revenue. Lottery proceeds support various programs, though critics note regressive impacts on lower-income players. These taxes prove politically easier than broad-based increases, though revenue volatility complicates budgeting.
Planning for Arizona taxes requires understanding your complete situation rather than focusing on single elements. The California executive celebrating income tax savings might face property tax shock on their Paradise Valley estate. The Illinois retiree escaping property taxes discovers transaction privilege tax on purchases previously exempt. The Nevada business owner enjoying no state income tax confronts TPT compliance complexity. Comprehensive planning considering all tax types optimizes overall burden while avoiding surprises.
Professional assistance proves valuable given Arizona’s complexity. CPAs familiar with Arizona-specific rules navigate credits and deductions visitors might miss. Enrolled agents provide year-round tax planning rather than just April filing assistance. Tax attorneys address complex business structures or dispute resolution. Property tax consultants help with assessments and appeals.
Timing matters in Arizona tax planning. Understanding assessment dates helps with property purchase timing. Business formation timing affects tax year obligations. Retirement account conversions might benefit from Arizona’s lower rates. Charitable contributions through Arizona tax credits provide greater benefit than federal deductions alone. Capital gains realization strategies consider Arizona’s partial subtraction for long-term gains. These timing considerations require advance planning rather than year-end scrambling.
Comparison shopping extends to tax implications. Choosing between neighboring cities might mean significant TPT differences. Home purchase decisions should factor property tax differences between similar properties. Business location affects both TPT obligations and potential incentives. Retirement community selection involves understanding taxing district variations.
The political landscape suggests continued tax evolution. Voter initiatives regularly propose tax changes—rate adjustments, new exemptions, targeted increases for education or infrastructure. Legislative sessions bring business tax incentive modifications and technical corrections. Court decisions clarify ambiguous provisions. Federal tax changes trigger Arizona conformity decisions. Staying informed through Arizona Department of Revenue publications and professional advisors ensures compliance while optimizing position.
For those relocating to Arizona, tax preparation begins before arrival. Establishing residency timing affects partial-year filing requirements. Understanding domicile rules prevents double taxation from former states. Business restructuring might benefit from Arizona’s favorable treatment of certain entities. Investment location strategies consider Arizona’s taxation of different income types. Vehicle registration timing minimizes overlapping obligations with other states. These transitional considerations reward advance planning over reactive compliance.
The Arizona tax story ultimately reflects broader Western values—preference for visible consumption taxes over hidden income taxes, local control over centralized authority, competitive positioning for economic growth. The system rewards those who understand its intricacies while functioning adequately for those who simply comply with obvious obligations. Whether Arizona’s tax structure provides net benefit depends entirely on individual circumstances, making personal analysis essential for informed relocation decisions.
We use cookies to improve your experience on our site. By using our site, you consent to cookies.
Manage your cookie preferences below:
Essential cookies enable basic functions and are necessary for the proper function of the website.
Statistics cookies collect information anonymously. This information helps us understand how visitors use our website.
Monetize your website by displaying targeted ads and earning revenue from clicks and impressions.
Google Analytics is a powerful tool that tracks and analyzes website traffic for informed marketing decisions.
Service URL: policies.google.com (opens in a new window)
You can find more information about our Cookie Policy and Privacy Policy.